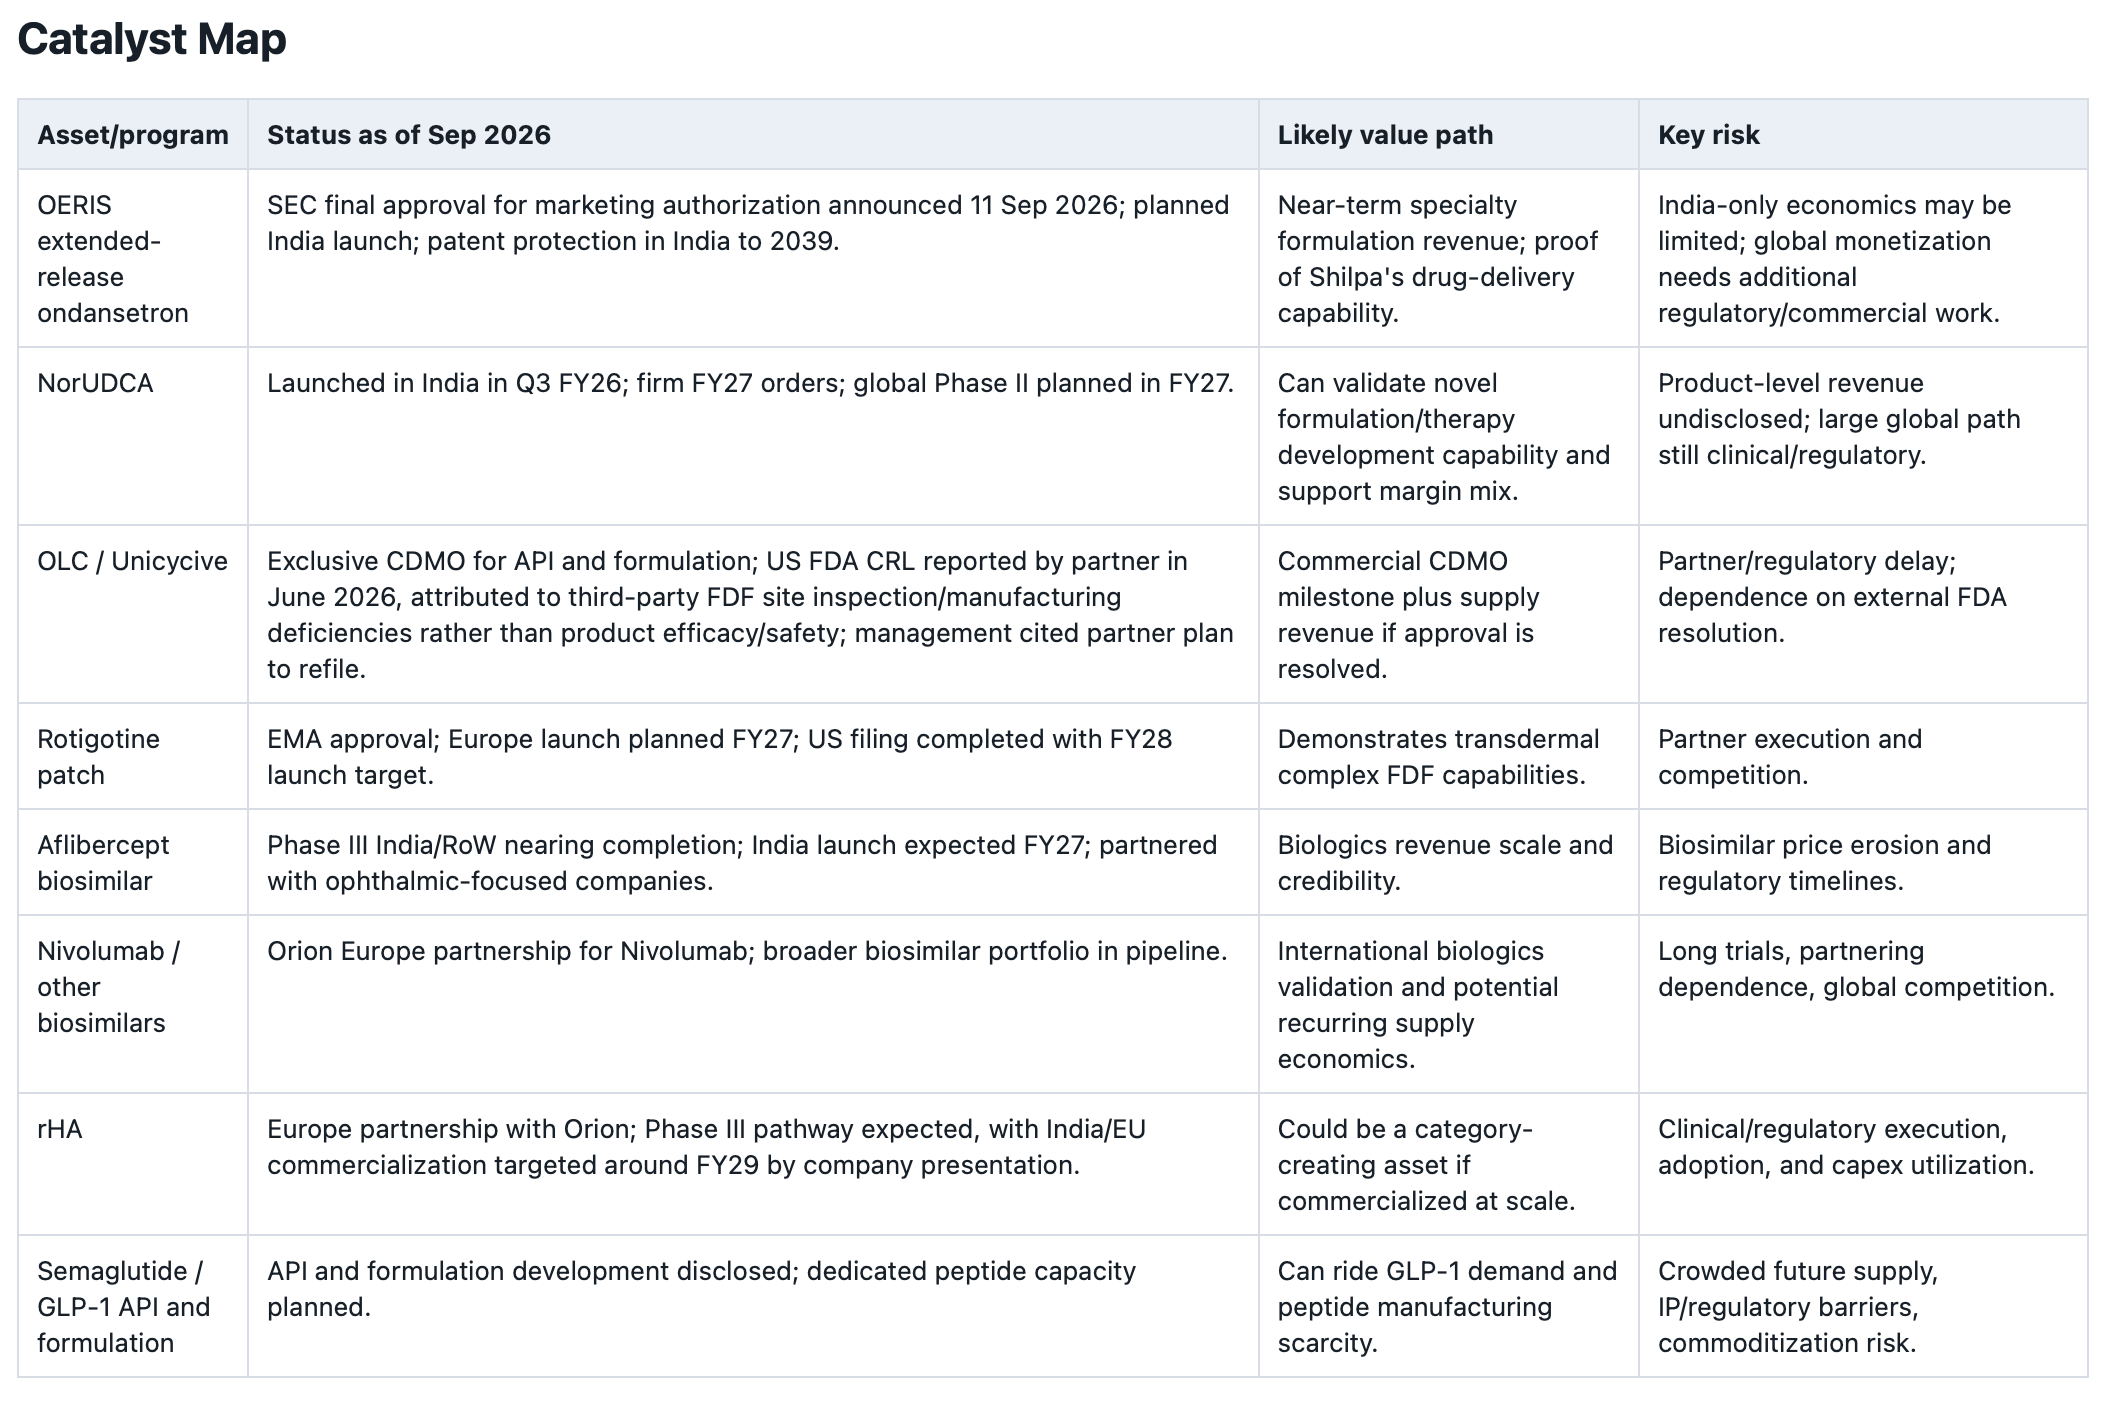
First the disclaimer
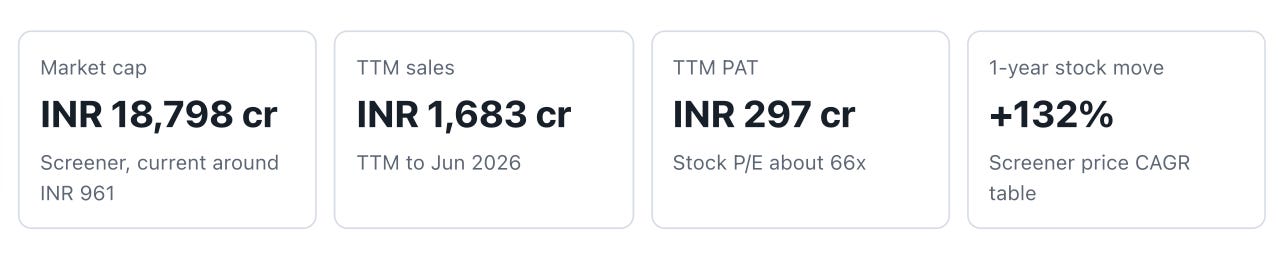
Prepared for: personal research use. Date: September 2026 Price: INR 961.15
Business Snapshot
Shilpa began as an API manufacturer and has long been associated with oncology. The current company is trying to become a broader specialty pharma and integrated CDMO platform across small molecules, formulations, biologics, ADCs, peptides and recombinant albumin.
Where the business is today
Q1 FY27 was the fourth consecutive record quarter for revenue and EBITDA. Consolidated revenue was INR 469 cr, EBITDA INR 139 cr, and EBITDA margin 30%. Reported PAT was INR 101 cr, helped by a tax reversal; management said normalized tax should move toward about 25%.
Segment evidence
Q1 FY27 segment momentum was broad: API revenue was INR 260 cr including captive demand, formulation revenue was INR 198 cr with more than 100% YoY growth, and biologics revenue was INR 52 cr with 42% YoY growth. The official presentation’s consolidated revenue breakup shows API INR 216 cr, formulations INR 198 cr and biologics INR 52 cr.
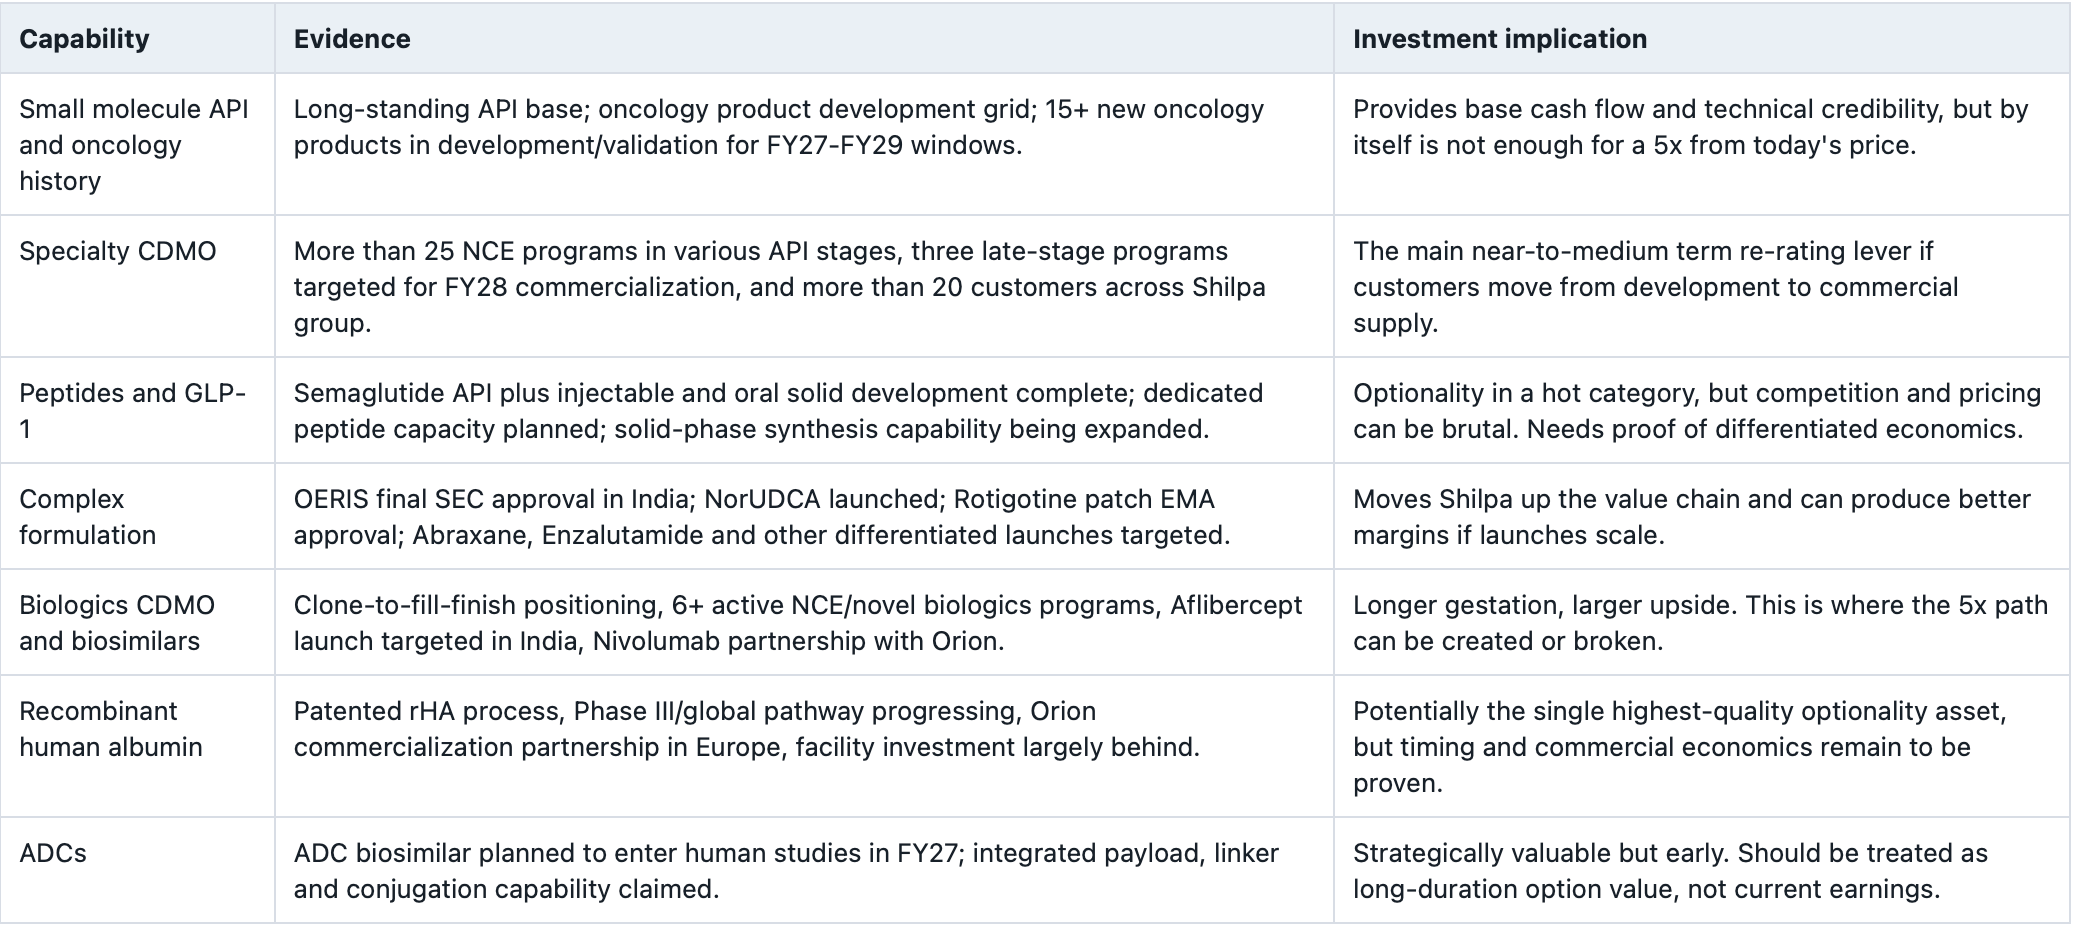
Why Capability Could Be Real
Shilpa’s positive case rests on breadth plus integration. Many Indian pharma companies can claim one piece of the puzzle: API chemistry, formulation development, injectables, biologics, or manufacturing services. Shilpa is unusual because it is attempting several of these under one operating architecture.